

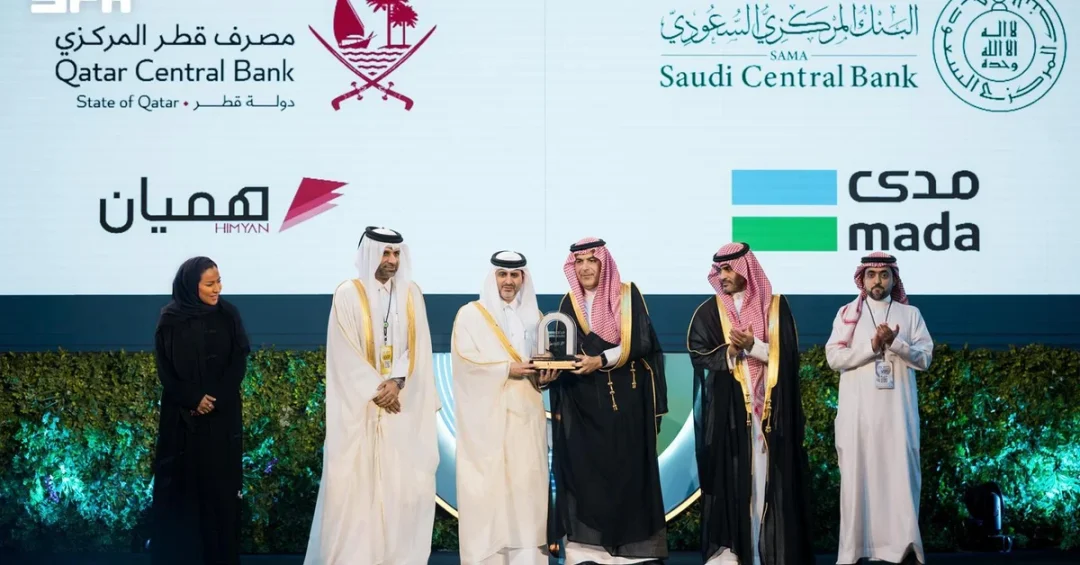
The Saudi Central Bank (SAMA), in cooperation with the Qatar Central Bank (QCB), has announced that the acceptance of Saudi Arabia’s national payment card “mada” in Qatar and Qatar’s national card “HIMYAN” in Saudi Arabia will be rolled out gradually, according to the Saudi Press Agency (SPA). The announcement, issued from Riyadh on September 15, 2026, marks a significant step in cross-border payment integration between the two Gulf states and reflects their continued cooperation in the financial sector.
Context and Background
The reciprocal acceptance of the two national payment cards is part of broader Gulf Cooperation Council (GCC) efforts to develop a shared payment infrastructure and expand the usability of national cards across member states. This initiative aligns with the strategic objectives of economic and financial integration among GCC countries.
The Gulf Payment Network (GCC-NET) serves as the technical backbone for this integration. It enables citizens and residents of GCC countries to withdraw cash from ATMs and make payments at POS terminals using GCC network debit cards. By facilitating easier, more efficient, and less costly transactions, the network aims to improve the quality of financial services across the region.
Key Details
Under the arrangement, holders of “mada” cards issued in Saudi Arabia will be able to use them at ATMs and POS terminals in Qatar, while holders of “HIMYAN” cards issued in Qatar will enjoy similar acceptance in Saudi Arabia. The rollout will be gradual, ensuring a smooth and secure implementation.
The cooperation between SAMA and QCB underscores the commitment of both countries to enhance payment systems and foster greater financial connectivity. It also represents a practical step toward realizing the vision of a more integrated Gulf economy.
Implications and Impact
The acceptance of national cards across borders is expected to bring tangible benefits to citizens, residents, and businesses in both countries. It simplifies travel and commerce by reducing reliance on international payment networks, which can be more expensive and less transparent. For consumers, this means greater convenience and potentially lower transaction fees. For businesses, it expands the customer base and streamlines payment processes.
On a regional level, the move strengthens financial ties between Saudi Arabia and Qatar and sets a precedent for further integration among GCC states. It supports the broader goal of economic diversification and resilience, key themes of Saudi Vision 2030.
Vision 2030 Alignment
This initiative aligns with Saudi Vision 2030’s objective of building a diversified and sustainable economy, including the development of a robust digital payments ecosystem. By enhancing cross-border payment interoperability, SAMA is contributing to the Kingdom’s ambition to become a global leader in financial technology and innovation. The gradual acceptance of “mada” in Qatar and “HIMYAN” in Saudi Arabia exemplifies the Kingdom’s proactive role in fostering regional cooperation and economic integration, reinforcing its position as a key player in the global financial landscape.
20 Questions
Q1. What was announced by SAMA and Qatar Central Bank?
A1. SAMA and the Qatar Central Bank announced the gradual acceptance of Saudi Arabia’s “mada” cards in Qatar and Qatar’s “HIMYAN” cards in Saudi Arabia, enhancing cross-border payment integration.
Q2. When was this announcement made?
A2. The announcement was made on September 15, 2026, from Riyadh, as reported by the Saudi Press Agency (SPA).
Q3. What is “mada”?
A3. “mada” is the national payment card scheme of Saudi Arabia, enabling domestic and, increasingly, international transactions for millions of users.
Q4. What is “HIMYAN”?
A4. “HIMYAN” is Qatar’s national payment card, facilitating electronic payments within Qatar and now, in Saudi Arabia.
Q5. Why is this development significant?
A5. It reflects growing financial integration between Saudi Arabia and Qatar, and supports joint GCC efforts to develop a shared payment infrastructure.
Q6. What is GCC-NET?
A6. GCC-NET is the Gulf Payment Network that enables cash withdrawals and POS payments across GCC countries using network debit cards.
Q7. How will the rollout be implemented?
A7. The acceptance will be rolled out gradually to ensure a smooth and secure implementation for all stakeholders.
Q8. What benefits does this bring to cardholders?
A8. Cardholders can withdraw cash from ATMs and make payments at POS terminals in the other country, with greater ease and potentially lower costs.
Q9. Does this affect businesses?
A9. Yes, businesses in both countries can accept a wider range of cards, simplifying transactions and potentially increasing sales from cross-border visitors.
Q10. How does this align with GCC objectives?
A10. It supports the GCC’s strategic goals of economic and financial integration, enhancing cooperation among member states.
Q11. What role does SAMA play in this initiative?
A11. SAMA, as Saudi Arabia’s central bank, oversees the acceptance of “HIMYAN” in the Kingdom and facilitates the use of “mada” in Qatar.
Q12. What role does Qatar Central Bank play?
A12. The Qatar Central Bank coordinates with SAMA to enable the acceptance of “mada” in Qatar and “HIMYAN” in Saudi Arabia.
Q13. Will there be any fees for using the cards abroad?
A13. The initiative aims to make payments less costly; specific fee structures will be determined by the banks and announced in due course.
Q14. How does this affect tourism and travel?
A14. It simplifies payments for travelers between the two countries, enhancing the overall travel experience and supporting tourism growth.
Q15. Is this part of a larger regional trend?
A15. Yes, it is part of broader GCC efforts to integrate payment systems and reduce reliance on international card networks.
Q16. What is the expected timeline for full implementation?
A16. The rollout is gradual; specific timelines will depend on technical and operational readiness, with updates from SAMA and QCB.
Q17. How does this benefit the Saudi economy?
A17. It enhances financial connectivity, supports digital payments, and aligns with Vision 2030 goals of economic diversification and innovation.
Q18. Will other GCC countries join this initiative?
A18. The initiative is part of GCC-wide efforts; other member states may participate as the network expands, following bilateral agreements.
Q19. What technology underpins this acceptance?
A19. The GCC Payment Network (GCC-NET) provides the infrastructure for cross-border ATM and POS transactions using national cards.
Q20. How does this reflect Saudi-Qatar relations?
A20. It demonstrates strong bilateral cooperation and shared commitment to regional financial integration, benefiting citizens and economies alike.
Reader Feedback
We value your thoughts. Please share your feedback on this article.
Your feedback helps us improve our coverage.